
Acupuncture Market Size, Share, Demand, Growth & Forecast 2026–2034
Market Overview
The global Acupuncture Market is experiencing steady growth as acupuncture becomes increasingly integrated into pain-management, complementary-care, wellness, and broader healthcare settings. Acupuncture is moving from a predominantly traditional-medicine practice toward a more integrated service, with strong commercial demand associated with recurring treatment for chronic pain, particularly musculoskeletal conditions. Demand also extends to headaches, migraine, selected neurological conditions, women’s health, stress and mental wellness, and other applications.
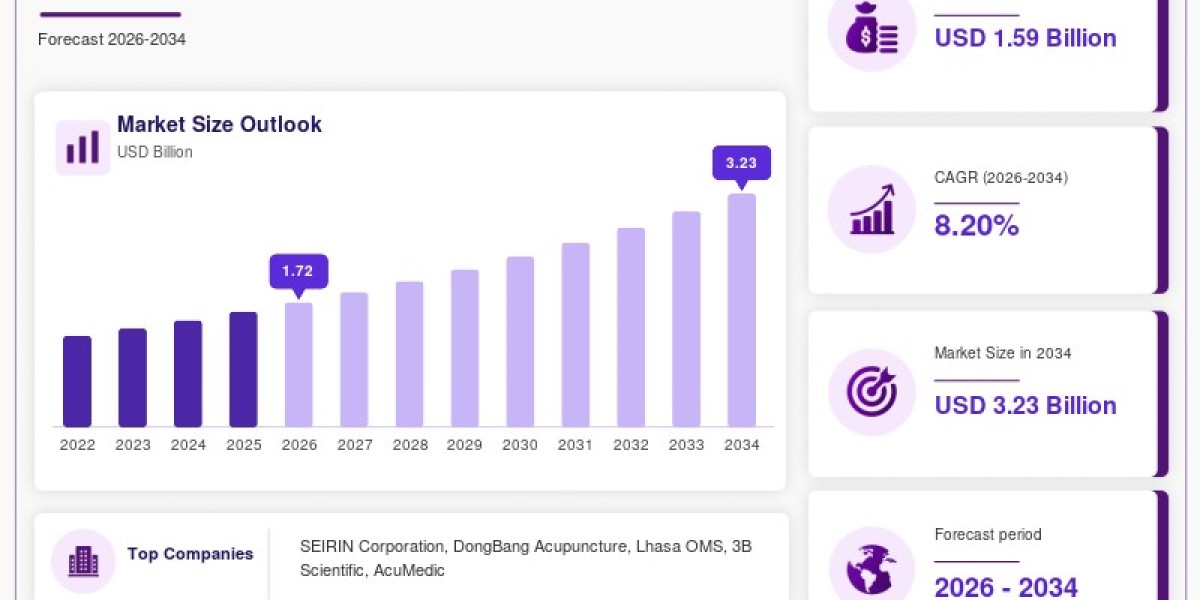
The global Acupuncture Market was valued at USD 1.59 billion in 2025 and is projected to grow from USD 1.72 billion in 2026 to USD 3.23 billion by 2034. The market is registering increasing institutional recognition, while evidence generation, safety, regulation, health-system integration, and qualified practitioner requirements are becoming important factors influencing market development.
Request Sample Link:
https://reedintelligence.com/market-analysis/acupuncture-market/request-sample
Market Size and Forecast
The global Acupuncture Market is projected to reach USD 3.23 billion by 2034 from USD 1.72 billion in 2026, registering a CAGR of 8.20% during the forecast period from 2026 to 2034.
Market development is closely associated with the growing use of acupuncture for chronic pain management and its integration into complementary and multidisciplinary healthcare services. The United States has also recorded increased acupuncture use, with acupuncture use among U.S. adults increasing from 1.0% in 2002 to 2.2% in 2022.
Institutional recognition is also influencing market development. In 2025, the World Health Organization adopted its Global Traditional Medicine Strategy 2025–2034, emphasizing evidence generation, safety and regulation, integration into health systems, and qualified practitioners.
Market Drivers
Growing Use of Acupuncture for Chronic Pain
Chronic pain represents the clearest demand mechanism for acupuncture services. Acupuncture is used for conditions including back and neck pain, knee osteoarthritis, migraine, and other painful conditions. Its inclusion among non-drug treatment options for chronic low-back pain is supporting utilization across pain-management and complementary-care settings.
The recurring nature of treatment for chronic conditions creates continuing demand for practitioner services and disposable acupuncture needles. Pain-management clinics and integrated-care providers therefore represent important demand centers.
Health-System Integration Creates New Referral Channels
The WHO Global Traditional Medicine Strategy 2025–2034 emphasizes evidence-based integration of traditional, complementary, and integrative medicine into health systems alongside stronger regulation, safety systems, and research.
This creates potential pathways for acupuncture to move from standalone complementary-care practices into broader healthcare services. Greater integration can support referrals, professional training, and institutional procurement of acupuncture supplies, although reimbursement and licensing requirements remain dependent on individual countries.
Wider Acceptance of Non-Drug Pain Management
Healthcare systems are evaluating non-pharmacological approaches alongside medication-based pain management. Acupuncture can function as an adjunct to conventional care, broadening its potential customer base to multidisciplinary clinics, rehabilitation providers, and pain-management centers.
Market Challenges
Uneven Reimbursement Limits Patient Access
Insurance coverage for acupuncture remains inconsistent. In the United States, Medicare covers acupuncture specifically for chronic low-back pain under defined conditions, including up to 12 visits within 90 days and up to eight additional sessions when improvement is demonstrated.
Where reimbursement is available, patient out-of-pocket costs can decline and providers can have a more predictable revenue pathway. Where coverage is absent, treatment depends more heavily on discretionary spending, making reimbursement policy an important market constraint.
Variation in Clinical Evidence and Practitioner Standards
Clinical evidence and treatment effects vary across indications. Acupuncture may provide benefits for several pain conditions, but evidence quality differs depending on the condition and treatment approach.
This creates demand for qualified practitioners, sterile single-use needles, and standardized treatment protocols. Differences in regulation, practitioner training, and professional standards across jurisdictions can also restrict market expansion.
Market Opportunities
Evidence-Based Integration Into Hospitals
Evidence-based integration into hospitals represents an opportunity for acupuncture providers, particularly in selected pain-management applications. Hospital-based programs can facilitate referrals from physicians and rehabilitation specialists while supporting standardized clinical protocols and practitioner credentials.
Electroacupuncture and Technology-Enabled Treatment
Electroacupuncture expands the market beyond manually manipulated needles by introducing electrical stimulation. This creates opportunities for suppliers of electrotherapy units, specialized needles, and clinical equipment.
Electroacupuncture is projected to grow at approximately 9.1% CAGR through 2034, exceeding the overall Acupuncture Market CAGR of 8.20%.
Standardized Disposable Needles
Acupuncture treatment requires needles and related clinical supplies on a recurring basis. Single-use sterile acupuncture needles in multiple configurations create a recurring consumables opportunity. Product differentiation includes sterility, insertion characteristics, gauge, packaging, and practitioner convenience.
Market Segmentation
The Acupuncture Market is segmented by Type, Application, End User, and Region.
By Type
Manual Acupuncture accounted for approximately 52% of the global market in 2025, making it the largest type segment. Its position reflects broad use of conventional needle insertion and manual stimulation across pain-management, musculoskeletal, and complementary-care settings.
Electroacupuncture represented approximately 24% of the market and is projected to grow at approximately 9.1% CAGR. Other acupuncture techniques accounted for the remainder of the market.
Manual Acupuncture
Manual Acupuncture remains the core treatment format and benefits from broad practitioner familiarity and comparatively straightforward equipment requirements. Recurring treatment sessions also generate continuing demand for sterile disposable needles.
Electroacupuncture
Electroacupuncture is the fastest-growing type segment, with projected growth of approximately 9.1% CAGR through 2034. The technique combines conventional needle placement with controlled electrical stimulation, creating demand for specialized equipment alongside needles.
By Application
Pain Management accounted for approximately 43% of the global market in 2025, making it the largest application. Musculoskeletal Disorders represented approximately 22%, Neurological Disorders accounted for approximately 12%, Women's Health represented 9%, Stress & Mental Wellness accounted for 8%, and other applications represented 6%.
Pain Management
Pain Management represents the largest application due to recurring treatment requirements associated with chronic conditions. Back and neck pain, knee osteoarthritis, and migraine are among the conditions associated with acupuncture use.
Musculoskeletal Disorders
Musculoskeletal Disorders accounted for approximately 22% of the market and are projected to grow at approximately 8.8% CAGR. Applications involving back pain, osteoarthritis, and related conditions support demand within this segment.
By End User
Hospitals & Clinics accounted for approximately 41% of the market in 2025. Specialty Acupuncture Centers represented approximately 34% and are projected to grow at approximately 8.7% CAGR. Wellness Centers accounted for approximately 17%, while Home Care represented approximately 8%.
Hospitals and clinics benefit from the potential integration of acupuncture into multidisciplinary pain-management and rehabilitation services. Specialty Acupuncture Centers benefit from specialized practitioner expertise and a treatment model centered specifically on acupuncture.
Regional Analysis
Asia-Pacific
Asia-Pacific accounted for approximately 44% of the global Acupuncture Market in 2025, making it the largest regional market. Established traditional-medicine use, practitioner networks, and complementary-medicine infrastructure provide a substantial service base.
Asia-Pacific is also the fastest-growing region, with approximately 9.0% CAGR through 2034. Growth is supported by established utilization, institutional integration, and increasing professionalization.
North America
North America represented approximately 25% of the market in 2025 and is projected to grow at approximately 7.7% CAGR. The United States is the principal market, supported by increasing reported acupuncture use and incorporation into selected healthcare pathways.
Europe
Europe accounted for approximately 18% of the market in 2025 and is projected to grow at approximately 7.5% CAGR. Demand is supported by complementary healthcare use, pain-management services, and interest in non-pharmacological interventions.
Latin America
Latin America represented approximately 8% of the market in 2025 and is projected to grow at approximately 7.0% CAGR. The market is centered primarily on private practices, complementary-health providers, and selected clinical applications.
Middle East & Africa
Middle East & Africa accounted for approximately 5% of the market in 2025 and is projected to grow at approximately 6.6% CAGR. Demand is concentrated in major urban healthcare centers, private clinics, and wellness facilities.
Key Players
SEIRIN Corporation
DongBang Acupuncture
Lhasa OMS
3B Scientific
AcuMedic
Schwa-medico
Wuxi Jiajian Medical Devices
Suzhou Medical Appliance Factory
SEIRIN differentiates through automated needle manufacturing, sterile single-use products, and multiple needle configurations, including J-Type, J-15, L-Type, G-Type, intradermal, and other needle formats.
Lhasa OMS occupies a distribution role, supplying professional acupuncture products and carrying brands including SEIRIN, DBC, Hwato, and Tai-Chi. Its broad catalog provides a route to market for multiple manufacturers and supports recurring practitioner purchases.
Recent Developments
In May 2025, Member States at the 78th World Health Assembly agreed on the WHO Global Traditional Medicine Strategy 2025–2034. The strategy emphasizes stronger evidence, safety and regulation, integration into health systems, and qualified practitioners.
WHO also published its Global Report on Traditional, Complementary and Integrative Medicine 2024 in December 2025. The report draws on responses from 106 Member States and examines governance, financing, health workforce, research, service models, and access to care.
Conclusion
The Acupuncture Market is projected to grow from USD 1.72 billion in 2026 to USD 3.23 billion by 2034, registering a CAGR of 8.20%. Growing use for chronic pain management, wider acceptance of non-drug treatment approaches, health-system integration, and increasing emphasis on evidence and professional standards will continue to influence market development.
Manual Acupuncture currently leads the type segment with approximately 52% of the market, while Pain Management leads applications with approximately 43%. Asia-Pacific remains the largest regional market with approximately 44% share and is projected to record the fastest CAGR of approximately 9.0% through 2034.
Overall, the Acupuncture Market continues to present opportunities across evidence-based healthcare integration, electroacupuncture, standardized disposable needles, pain-management services, and technology-enabled treatment as the market develops within increasingly structured healthcare and regulatory environments.
Report Link:
https://reedintelligence.com/market-analysis/acupuncture-market