
Assisted Reproductive Technology Market Size, Share & Trends Analysis Report 2026–2034
Market Overview
The Assisted Reproductive Technology Market is expanding as demand for infertility diagnosis and treatment continues to increase and fertility care develops into a broader ecosystem of clinical, laboratory, genetic, and cryopreservation services. Assisted reproductive technology includes procedures and services such as in vitro fertilization (IVF), intracytoplasmic sperm injection (ICSI), frozen embryo transfer, cryopreservation, donor procedures, embryo culture, genetic testing, and related laboratory technologies.
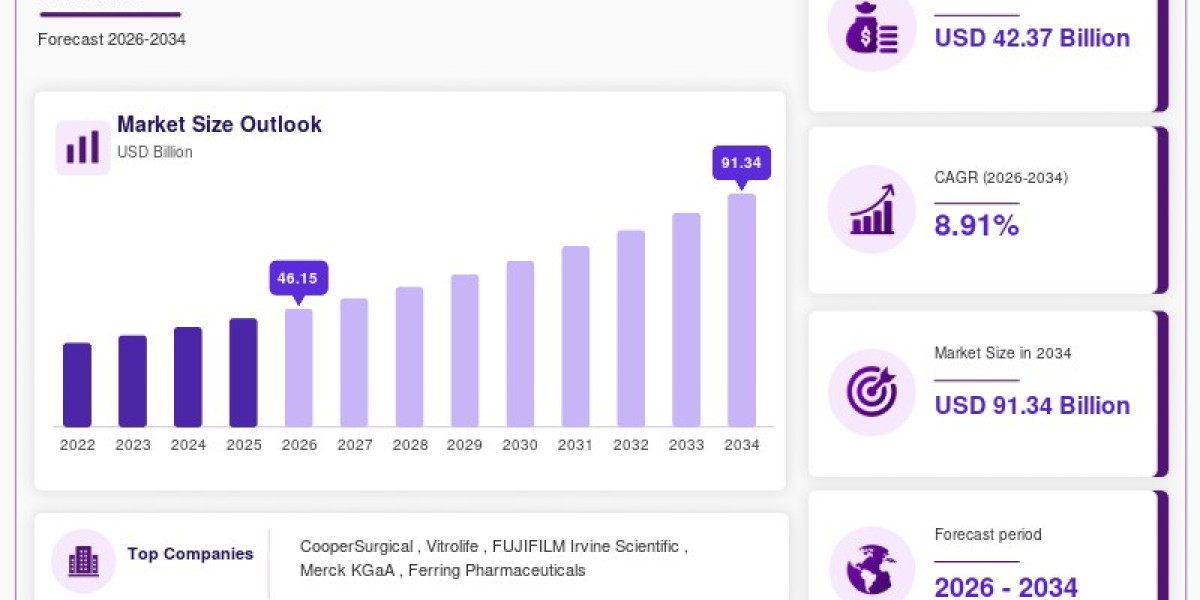
The Assisted Reproductive Technology Market was valued at USD 42.37 billion in 2025 and is estimated at USD 46.15 billion in 2026. The market is projected to reach USD 91.33 billion by 2034, expanding at a CAGR of 8.91% during 2026–2034.
The market is increasingly linked not only to the number of ART treatment cycles but also to the complexity and number of laboratory services associated with each treatment cycle. Fertility clinics, hospitals, IVF centers, and research institutions are therefore contributing to demand for specialized laboratory equipment, cryostorage systems, reproductive genetics, culture media, and embryo-assessment technologies.
Request Sample Link:
https://reedintelligence.com/market-analysis/assisted-reproductive-technology-market/request-sample
Market Size and Forecast
The Assisted Reproductive Technology Market is estimated at USD 46.15 billion in 2026 and is projected to reach USD 91.33 billion by 2034. The market is expected to expand at a CAGR of 8.91% during 2026–2034.
The market's development is supported by increasing demand for infertility care and the expansion of treatment pathways beyond conventional IVF. A single clinical episode can generate demand for ovarian stimulation, oocyte retrieval, fertilization, embryo culture, genetic testing, cryopreservation, and subsequent embryo-transfer procedures.
The increasing use of embryo and egg cryopreservation is also contributing to recurring treatment activity. Cryopreserved embryos can support future frozen embryo transfer procedures, while fertility preservation allows treatment demand to extend over longer periods.
Market Drivers
Rising Demand for Infertility Diagnosis and Treatment
The persistent need for infertility care is a fundamental driver of the Assisted Reproductive Technology Market. Increasing numbers of patients entering fertility-care pathways create demand across IVF, ovarian stimulation, oocyte retrieval, embryo culture, genetic testing, cryopreservation, and frozen embryo transfer services.
Fertility clinics and specialized IVF centers can benefit from broader treatment pathways because additional procedures increase utilization of embryology laboratories, cryostorage infrastructure, and reproductive-genetics services.
Expansion of Embryo Cryopreservation and Frozen Treatment Cycles
Cryopreservation has become an important component of ART because eggs and embryos can be preserved for later treatment. Egg and embryo banking allows patients to defer treatment while maintaining access to stored reproductive material.
This supports demand for vitrification media, cryostorage systems, embryo-transfer products, laboratory software, and monitoring infrastructure.
Increasing Use of Laboratory and Embryo-Selection Technologies
ART laboratories are becoming increasingly technology intensive. Developments in genomics, transcriptomics, proteomics, metabolomics, time-lapse imaging, and artificial intelligence are contributing to advances in embryo evaluation and laboratory workflows.
Technologies such as time-lapse incubation, embryo-analysis software, genetic testing, and decision-support systems are becoming increasingly integrated into fertility-clinic operations.
Market Challenges
High Treatment Costs and Unequal Access
High treatment costs remain an important constraint on ART adoption. Affordability can create a gap between clinical need and treatment demand, particularly when patients are required to pay substantial treatment costs directly.
Patients may postpone treatment, select lower-cost alternatives, or discontinue treatment following unsuccessful cycles. Markets with stronger insurance or public financing can therefore convert underlying infertility demand into treatment volumes more effectively than markets where patients bear most costs directly.
Clinical, Regulatory and Laboratory Complexity
ART requires specialized reproductive endocrinologists, embryologists, laboratory infrastructure, controlled environments, and regulated handling of reproductive material. Shortages of equipment and trained personnel can restrict fertility-care availability.
Regulatory requirements also differ across jurisdictions, particularly regarding embryo handling, genetic testing, donor gametes, cryostorage, and treatment eligibility. These variations can increase operating costs and affect the introduction of new technologies.
Market Opportunities
Fertility Preservation and Cryostorage
Fertility preservation creates opportunities for longer-duration relationships between patients and ART providers. Egg and embryo banking can generate recurring demand for vitrification products, cryogenic storage, monitoring, thawing, and transfer services.
The continued development of cryopreservation technologies can therefore expand the commercial scope of ART beyond the initial treatment cycle.
AI-Enabled Embryo Assessment
AI-assisted embryo evaluation represents an emerging opportunity within the ART laboratory segment. Advanced embryo-assessment technologies can support image analysis, workflow consistency, structured embryo-development data, and embryologist decision-making.
The integration of embryo imaging with laboratory information systems also creates opportunities for increasingly connected fertility-laboratory workflows.
Expansion of Fertility Care in Underserved Markets
The expansion of fertility services in underserved markets creates opportunities for lower-cost IVF protocols, scalable laboratory equipment, training, decentralized fertility services, and technologies that reduce the infrastructure requirements associated with establishing new IVF centers.
Market Segmentation
The Assisted Reproductive Technology Market is segmented by Procedure, End User, and Region.
By Procedure
In Vitro Fertilization (IVF)
IVF is modelled as the largest procedure segment, accounting for approximately 46% of the 2025 market, equivalent to about USD 19.49 billion. IVF remains central to ART because it provides the clinical pathway for several associated services, including fertilization, embryo culture, embryo transfer, and cryopreservation.
Using an internally modelled 8.5% CAGR, the IVF segment would reach approximately USD 40.61 billion by 2034 under the supplied global market framework.
Intracytoplasmic Sperm Injection (ICSI)
ICSI is modelled at approximately 24% of the 2025 market, or USD 10.17 billion, with an internally assigned 9.5% CAGR. Its commercial relevance is linked to its integration into IVF laboratory workflows and specialized fertilization procedures.
Frozen Embryo Transfer
Frozen embryo transfer is modelled at 13% of the 2025 market, representing approximately USD 5.51 billion. Its importance is associated with the increasing use of cryopreserved embryos and treatment demand beyond the initial retrieval and embryo-development cycle.
Cryopreservation
Cryopreservation is modelled at 10% of the 2025 market, or approximately USD 4.24 billion. The segment includes technologies and services used to preserve eggs and embryos for future treatment.
Donor and Other ART Procedures
Donor and other ART procedures are modelled at 7% of the 2025 market, equivalent to approximately USD 2.97 billion. The category includes treatment pathways involving donor eggs or embryos and other less prevalent ART approaches.
By End User
Fertility clinics represent the core end-user environment, combining patient management with specialized embryology laboratories, reproductive endocrinology, and embryo-transfer capabilities.
Hospitals remain important where fertility services are integrated with reproductive medicine, gynecology, and broader women's-health services. Specialized IVF centers also have strong incentives to invest in laboratory automation, embryo culture, cryopreservation, and reproductive genetics.
Research and academic institutions contribute to the development and validation of embryo culture, reproductive genetics, cryobiology, imaging, and AI-based assessment technologies.
Regional Analysis
North America
North America accounts for approximately 31% of the 2025 market, equivalent to USD 13.13 billion. The region benefits from established ART infrastructure, fertility-clinic networks, sophisticated embryology laboratories, and adoption of reproductive-genetics and laboratory technologies.
Europe
Europe represents approximately 26% of the 2025 market, representing USD 11.02 billion. The region has a mature fertility-care ecosystem and strong clinical and research infrastructure. Demand is supported by IVF centers, reproductive genetics, cryopreservation, and laboratory technologies.
Asia-Pacific
Asia-Pacific represents approximately 28% of the 2025 market, or USD 11.86 billion. The region is modelled as the fastest-growing regional allocation at a CAGR of 10.2%. Growth is supported by expanding fertility-clinic infrastructure, increasing awareness of infertility treatment, and development of specialized reproductive-health services.
Latin America
Latin America represents approximately 8% of the 2025 market, equivalent to USD 3.39 billion. Expansion potential is associated with increasing availability of fertility services through private clinics and specialist reproductive centers.
Middle East and Africa
The Middle East and Africa represents approximately 7% of the 2025 market, or USD 2.97 billion. Demand is concentrated in markets with established specialist fertility centers, while broader adoption is influenced by healthcare infrastructure, affordability, regulation, and availability of trained embryologists.
Key Players
CooperSurgical
Vitrolife
FUJIFILM Irvine Scientific
Merck KGaA
Ferring Pharmaceuticals
Organon
Cook Medical
Hamilton Thorne
Other companies identified in the supplied market data include Natera and Sartorius.
CooperSurgical has a broad fertility portfolio covering IVF media, laboratory equipment, micromanipulation, cryopreservation, genetic services, and ART management. Vitrolife is active in embryo culture, time-lapse imaging, and embryo-analysis technologies.
Recent Developments
WHO issued its first global guideline on infertility in November 2025, providing 40 recommendations covering prevention, diagnosis, and treatment and calling for stronger integration of fertility care into national health systems and financing.
AI-supported embryo assessment is also becoming commercially integrated into IVF laboratory workflows, with technologies such as Vitrolife's iDAScore designed to automate embryo-image analysis and support embryo prioritization.
Conclusion
The Assisted Reproductive Technology Market is projected to grow from USD 46.15 billion in 2026 to USD 91.33 billion by 2034 at a CAGR of 8.91%. Rising demand for infertility diagnosis and treatment, expanding cryopreservation and frozen treatment cycles, increasing use of laboratory technologies, and continued development of embryo-selection solutions are supporting market expansion.
IVF currently represents the largest procedure segment at approximately 46% of the 2025 market, while fertility clinics remain a core end-user environment. North America accounts for approximately 31% of the 2025 market, while Asia-Pacific represents 28% and is modelled as the fastest-growing regional allocation at a CAGR of 10.2%.
Overall, the Assisted Reproductive Technology Market presents opportunities across fertility preservation, cryostorage, AI-enabled embryo assessment, laboratory technologies, reproductive genetics, and the expansion of fertility-care services into underserved markets.
Report Link:
https://reedintelligence.com/market-analysis/assisted-reproductive-technology-market