
Card Stock Market Size, Share & Trends Analysis Report 2026–2034
Market Overview
The Card Stock Market is supported by demand for heavier and more rigid paper grades used in applications where standard printing paper does not provide sufficient stiffness, surface quality, or presentation characteristics. Commercial printing, packaging, business communications, invitations, greeting products, labels, educational materials, and craft applications form the principal demand base.
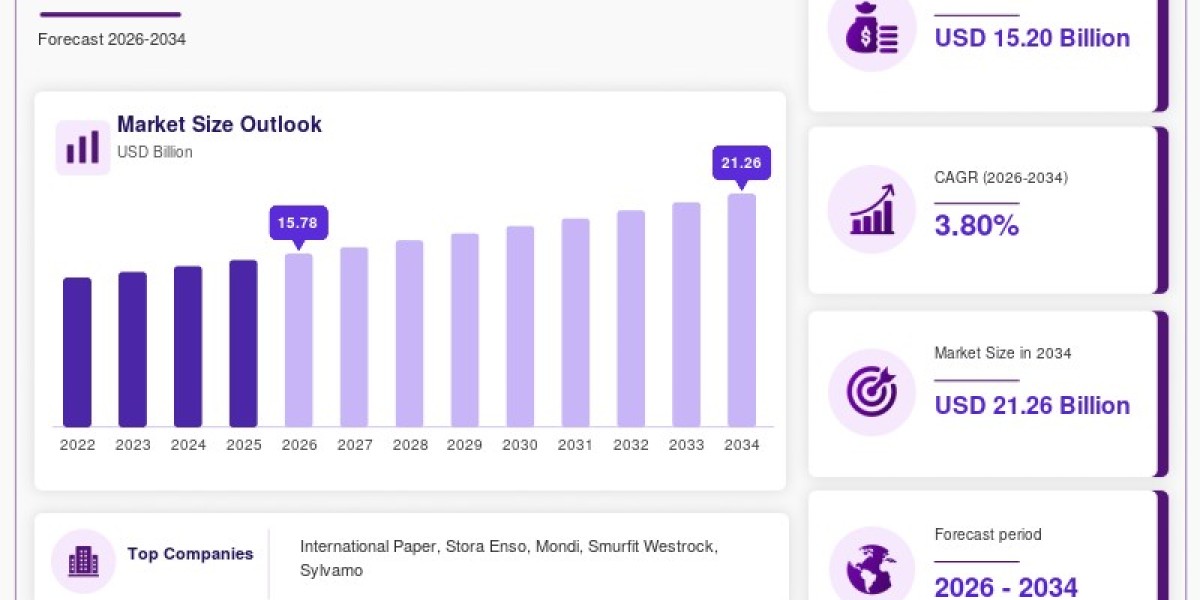
The global Card Stock Market was valued at USD 15.20 billion in 2025 and continues to be influenced by traditional paper consumption and the continued use of paperboard-based formats in consumer-facing applications. Packaging remains an important demand mechanism, with global cartonboard consumption increasing in 2025 according to Stora Enso. The market is also being shaped by sustainability requirements and demand for recyclable fiber-based materials.
Request Sample Link:
https://reedintelligence.com/market-analysis/card-stock-market/request-sample
Market Size and Forecast
The global Card Stock Market was valued at USD 15.20 billion in 2025 and is projected to grow from USD 15.80 billion in 2026 to USD 21.26 billion by 2034, registering a CAGR of 3.80% during the forecast period from 2026 to 2034.
Market development is supported by demand for rigid paper grades across packaging, printing, stationery, business communications, invitations, and specialty applications. Packaging provides an important physical-use case because card stock combines stiffness, printability, and fiber-based characteristics.
The market is also influenced by the development of recyclable and sustainable paper products. Increasing attention to recyclability and design-for-recycling requirements is encouraging manufacturers to focus on grades that combine functionality with improved environmental attributes.
Market Drivers
Packaging Applications Expand Demand for Rigid Paper Grades
Card stock benefits from applications requiring greater stiffness and printability than conventional paper. Packaging, product inserts, tags, presentation materials, and folding formats use heavier paper grades because structural performance and surface appearance influence the finished product.
Stora Enso reported increased global cartonboard consumption in 2025, while its consumer board deliveries also increased year over year. Mondi likewise identifies continuing customer demand for sustainable packaging and paper solutions.
Sustainability Requirements Strengthen Demand
Environmental requirements are influencing purchasing specifications for paper and paperboard products. The EU Packaging and Packaging Waste Regulation establishes recyclability requirements, with additional design-for-recycling requirements taking effect from 2030.
Mondi reported that 88% of its 2025 revenue came from reusable, recyclable, or compostable products, compared with 74% in its 2020 baseline year. These developments create opportunities for card-stock grades that combine printability, stiffness, and recyclability.
Premium Printing and Specialty Paper Applications
Business cards, invitations, greeting products, luxury packaging, certificates, promotional materials, and specialty stationery continue to use heavier stocks because rigidity and surface finish influence handling and presentation.
This creates demand based on the presentation characteristics of the material rather than commodity paper consumption. However, digital communications and electronic documents continue to limit some conventional printing applications.
Market Challenges
Digitalization Reduces Conventional Print Consumption
Digital communication continues to reduce demand for applications that historically consumed substantial quantities of printing paper. Stora Enso reported declining European publication paper demand in 2025, reflecting structural demand erosion alongside macroeconomic uncertainty.
The impact on card stock varies by application because packaging, invitations, business cards, and specialty printing remain physical products, while documents and some commercial communications can be digitized.
Paper and Board Overcapacity
Supply-side capacity remains an important constraint. Stora Enso reported that the global cartonboard market remained oversupplied in 2025, partly because of increased capacity, particularly in China.
Oversupply can increase competition among mills and converters, placing pressure on utilization, pricing, and producer margins. Efficient production, differentiated grades, and customer relationships therefore remain important considerations for card-stock producers.
Market Opportunities
Recyclable Specialty Grades
The shift toward recyclable packaging and paper products creates opportunities for manufacturers to develop card-stock grades combining stiffness, print performance, and improved environmental attributes.
Card-stock suppliers can target premium packaging, retail inserts, stationery, and printed promotional products where customers require both physical performance and sustainability credentials.
Flexible Production for Premium and Short-Run Printing
Digital printing and short-run commercial production create opportunities for suppliers able to provide consistent surface characteristics across specialized grades. Customized invitations, business cards, labels, promotional materials, and small-batch packaging can support demand for specialized card stock.
Market Segmentation
The Card Stock Market is segmented by Product Type, Weight, Application, Distribution Channel, and Region.
By Product Type
Coated Card Stock accounted for approximately 39% of the global market in 2025. Its position is associated with applications where image reproduction, smoothness, color consistency, and presentation quality are important.
Recycled Card Stock represented approximately 22% of the market in 2025 and is projected to expand at about 4.8% CAGR through 2034. Its expansion is connected to demand for recycled-fiber content and increasing attention to circular-material procurement.
Uncoated Card Stock is projected to grow at approximately 3.4% CAGR, while Specialty Card Stock is projected to grow at approximately 4.2% CAGR through 2034.
By Weight
Mediumweight Card Stock accounted for approximately 46% of the market in 2025. It provides a balance between rigidity, printability, handling, and material cost across multiple applications.
Heavyweight Card Stock accounted for approximately 31% of the market in 2025 and is projected to grow at about 4.5% CAGR through 2034. Lightweight Card Stock is projected to grow at approximately 3.1% CAGR through 2034.
By Application
Printing & Publishing accounted for approximately 32% of the global market in 2025. Packaging accounted for approximately 28% and is the fastest-growing major application, expanding at about 4.7% CAGR through 2034.
Stationery & Crafts is projected to grow at approximately 3.7% CAGR, Business Cards & Invitations at 3.2%, and Others at approximately 2.9% CAGR through 2034.
By Distribution Channel
Direct Sales accounted for approximately 43% of the market in 2025. Online Channels accounted for approximately 17% and are projected to grow at about 5.2% CAGR through 2034.
Specialty Stores are projected to grow at approximately 3.6% CAGR, while Office Supply Stores are projected to grow at approximately 2.8% CAGR through 2034.
Regional Analysis
Asia-Pacific
Asia-Pacific accounted for approximately 34% of the global market in 2025 and is projected to grow at about 4.6% CAGR through 2034. The region benefits from its large manufacturing, printing, packaging, and consumer-goods base. China is particularly important because of its extensive paper and packaging production capacity.
North America
North America accounted for approximately 27% of the global market in 2025 and is projected to grow at about 3.5% CAGR through 2034. Demand is supported by commercial printing, packaging, stationery, greeting products, and business communications.
Europe
Europe represented approximately 23% of the market in 2025 and is projected to grow at about 3.1% CAGR through 2034. Demand is shaped by established printing industries and packaging applications, while sustainability regulation is becoming increasingly important in product selection.
Latin America
Latin America represented approximately 10% of the market in 2025 and is projected to grow at about 3.6% CAGR through 2034. Demand is connected to retail packaging, food and consumer-product presentation, commercial printing, and stationery.
Middle East & Africa
Middle East & Africa accounted for approximately 6% of the market in 2025 and is projected to grow at about 3.2% CAGR through 2034. Demand is supported by commercial printing, education, retail packaging, hospitality-related materials, and stationery.
Key Players
International Paper
Stora Enso
Mondi
Smurfit Westrock
Sylvamo
Fedrigoni
Sappi
UPM
Stora Enso is expanding its consumer-packaging-board position through its Oulu investment in Finland. The new line has annual capacity of 750,000 tonnes and is designed to produce folding box board and coated unbleached kraft.
Mondi is positioning its paper and packaging portfolio around recyclable and sustainable materials while continuing targeted investments in production assets. The company reported that 88% of its 2025 revenue came from reusable, recyclable, or compostable products.
Recent Developments
In March 2025, Stora Enso began production ramp-up of its new consumer packaging board line at Oulu, Finland. The line is designed for folding box board and coated unbleached kraft, with annual capacity of 750,000 tonnes.
In 2025, the EU adopted Regulation 2025/40 establishing requirements covering packaging sustainability, recyclability, and design for recycling. The regulation includes paper and cardboard within its packaging-material framework.
Conclusion
The Card Stock Market is projected to grow from USD 15.80 billion in 2026 to USD 21.26 billion by 2034, registering a CAGR of 3.80% during the forecast period. Demand is supported by packaging applications, premium printing, specialty paper requirements, and increasing attention to recyclable fiber-based materials.
Coated Card Stock currently represents approximately 39% of the market, while Mediumweight Card Stock accounts for approximately 46%. Packaging is the fastest-growing major application, expanding at about 4.7% CAGR through 2034. Asia-Pacific represents the largest regional market and is projected to grow at about 4.6% CAGR through 2034.
The Card Stock Market continues to present opportunities across recyclable specialty grades, premium packaging, short-run printing, stationery, and other applications where stiffness, printability, presentation, and sustainability are important product characteristics.
Report Link:
https://reedintelligence.com/market-analysis/card-stock-market