
Audio Market Size, Share & Trends Analysis Report By Product Type, Technology, Application, Distribution Channel and Region, 2026–2034
Market Overview
The global Audio Market is evolving from standalone sound-reproduction equipment toward connected personal, home, automotive, professional, and assistive audio ecosystems. Wireless headphones and earbuds, networked speakers, soundbars, automotive audio systems, and professional equipment increasingly combine acoustic hardware with software, connectivity, and intelligent processing.
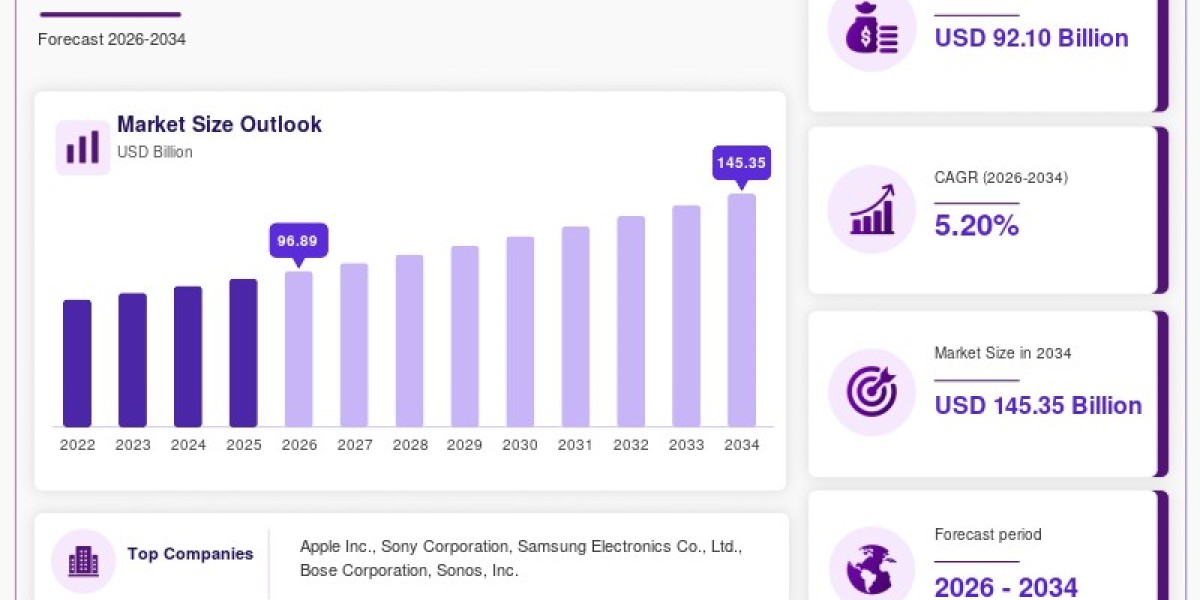
The global Audio Market was valued at USD 92.10 billion in 2025 and is projected to grow from USD 95.40 billion in 2026 to USD 145.35 billion by 2034. The market is expected to register a CAGR of 5.20% during the forecast period from 2026 to 2034.
The continued migration from wired to wireless listening is one of the most important changes in the market. Consumers increasingly expect compact audio devices to provide active noise cancellation, spatial audio, voice interaction, and smartphone integration. Wireless connectivity, intelligent processing, and multifunctional product features are therefore reshaping the Audio Market.
Request Sample Link:
https://reedintelligence.com/market-analysis/audio-market/request-sample
Market Size and Forecast
The global Audio Market is projected to increase from USD 95.40 billion in 2026 to USD 145.35 billion by 2034, registering a CAGR of 5.20% during 2026–2034.
The market is being supported by the expansion of connected personal audio, home audio, automotive systems, professional equipment, and smart speakers. Bluetooth LE Audio is also contributing to the development of lower-power wireless applications, hearing-aid connectivity, and Auracast broadcast audio.
Product functionality is increasingly expanding beyond conventional playback. Features such as active noise cancellation, spatial audio, personalization, voice processing, and hearing-related capabilities are creating additional value in premium audio products.
Market Drivers
Wireless Connectivity Is Expanding Personal Audio
Wireless connectivity is changing purchasing behavior by eliminating physical connections between smartphones and listening devices while enabling additional software-driven features. Bluetooth LE Audio provides a lower-power architecture and supports applications including hearing aids and Auracast broadcast audio.
Wireless products can incorporate active noise cancellation, spatial audio, multipoint connectivity, voice assistants, and health-related functions. This allows manufacturers to differentiate products through software and signal processing.
Premium Audio Devices Are Adding Software-Enabled Features
Audio manufacturers are increasingly competing through computational audio in addition to speakers, drivers, and amplifiers. Spatial audio, adaptive noise cancellation, personalization, voice processing, and hearing-related functions create additional reasons for consumers to upgrade.
The integration of multiple functions into a single device allows manufacturers to create premium product tiers while software updates can extend product capabilities after purchase.
Auracast Is Creating New Public and Commercial Audio Use Cases
Auracast expands Bluetooth audio from one-to-one connections toward broadcast communication. The technology enables a transmitter to send audio to nearby compatible receivers, including earbuds, speakers, and hearing devices.
Potential applications include theaters, museums, universities, stadiums, transportation facilities, and other public environments. This creates additional opportunities involving transmitters, receivers, venue infrastructure, and accessibility-oriented audio applications.
Market Challenges
Short Product Cycles Increase Replacement Pressure
Rapid product launches in headphones, earbuds, speakers, and connected audio devices can shorten perceived product lifecycles. Consumers increasingly compare products based on battery performance, wireless standards, software functionality, and ecosystem compatibility.
Manufacturers must continuously invest in product development, acoustic engineering, and software integration. Inventory and component-management risks can also increase when new product generations are introduced quickly.
Fragmented Standards and Ecosystems Complicate Interoperability
Audio products increasingly operate across Bluetooth, Wi-Fi, proprietary wireless technologies, mobile operating systems, and streaming platforms. Although standards such as Bluetooth LE Audio are designed to improve interoperability, implementation depends on device capabilities and manufacturer strategies.
The transition toward technologies such as Auracast can create additional development and certification complexity, while consumers may delay purchases when compatibility between new features and existing devices is unclear.
Market Opportunities
Hearing-Enabled Consumer Audio
The integration of hearing-health functions into mainstream earbuds is creating an opportunity at the intersection of consumer electronics and assistive listening. Hearing-related functions combined with wireless connectivity can allow familiar consumer devices to support multiple daily audio activities.
This opportunity is particularly relevant to premium earbuds, hearing devices, smartphones, and audio-processing software, although regulatory approval, clinical requirements, and regional feature availability can affect adoption.
Public-Space Broadcast Audio
Auracast creates potential infrastructure opportunities for venues requiring accessible and personalized audio. Applications can include guided tours, presentations, entertainment, and accessibility services.
The opportunity extends beyond consumer headphones into professional audio transmitters, installation services, and venue-management systems. Adoption remains dependent on compatible receivers and venue investment cycles.
Market Segmentation
The Audio Market is segmented by Product Type, Technology, Application, Distribution Channel, and Region.
By Product Type
Headphones & Earphones
Headphones & Earphones accounted for approximately 42% of the product-type segment in 2025. Personal audio benefits from frequent daily usage, smartphone integration, and rapid feature development.
Wireless earbuds and headphones increasingly combine ANC, microphones, spatial audio, voice interaction, and health-related functionality. The recurring replacement cycle supports demand as consumers seek improved battery life, comfort, sound quality, and connectivity.
Smart Speakers
Smart Speakers accounted for approximately 13% of the product-type segment in 2025 and are projected to grow at approximately 7.1% CAGR through 2034. Growth is linked to voice interfaces, smart-home control, streaming services, and multi-room audio.
Home Audio Systems
Home Audio Systems represented approximately 21% of the product segment in 2025 and are projected to grow at approximately 4.7% CAGR. Connected home entertainment and audio ecosystems support continued demand.
Professional Audio Equipment
Professional Audio Equipment represented approximately 15% of the product segment in 2025 and is projected to grow at approximately 5.4% CAGR. Professional applications continue to support demand for specialized audio equipment.
Portable Speakers
Portable Speakers represented approximately 9% of the product segment in 2025 and are projected to grow at approximately 6.3% CAGR, supported by demand for portable and connected audio solutions.
By Technology
Wireless audio accounted for approximately 69% of the technology segment in 2025. Bluetooth connectivity, smartphone integration, and the elimination of cables have established wireless devices as the principal format for personal audio.
Wireless technology is projected to grow at approximately 6.4% CAGR through 2034, compared with approximately 2.8% CAGR for wired audio.
Wired equipment continues to serve applications where reliability, low latency, professional monitoring, and high-fidelity connections are important.
By Application
Consumer applications accounted for approximately 54% of the application segment in 2025. Demand is supported by smartphones, streaming entertainment, gaming, home theater, and personal listening.
Automotive audio accounted for approximately 19% of the application segment in 2025 and is projected to grow at approximately 6.8% CAGR through 2034.
Commercial applications represented approximately 16% and are projected to grow at approximately 5.2% CAGR, while Professional applications represented approximately 11% and are projected to grow at approximately 4.8% CAGR.
By Distribution Channel
The Audio Market is segmented into Online and Offline distribution channels.
By Region
The market covers North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa.
Regional Analysis
North America
North America accounted for approximately 31% of global revenue in 2025. The region benefits from high consumer-electronics adoption, established premium audio brands, strong streaming consumption, and demand for connected home and personal devices.
The United States is the principal market, supported by adoption of wireless headphones, smart speakers, home-theater equipment, and professional audio systems.
Asia-Pacific
Asia-Pacific accounted for approximately 29% of global revenue in 2025 and is projected to grow at approximately 6.4% CAGR through 2034. China, Japan, South Korea, and India are important markets, while Southeast Asia provides additional consumer-electronics demand.
The region also has strategic importance in the audio value chain because major electronics manufacturers, component suppliers, and device-assembly operations are concentrated across Asian markets.
Europe
Europe accounted for approximately 24% of global revenue in 2025 and is projected to grow at approximately 4.8% CAGR through 2034. Demand is supported by premium consumer electronics, professional audio, automotive sound systems, and public-sector accessibility applications.
Latin America
Latin America accounted for approximately 10% of global revenue in 2025 and is projected to grow at approximately 5.3% CAGR through 2034. Brazil and Mexico represent the principal markets, supported by smartphone adoption, streaming entertainment, and increasing use of wireless personal audio.
Middle East & Africa
Middle East & Africa accounted for approximately 6% of global revenue in 2025 and is projected to grow at approximately 5.8% CAGR through 2034. Demand is concentrated in higher-income markets such as the United Arab Emirates and Saudi Arabia, while South Africa provides an important market in the broader African region.
Key Players
Apple Inc.
Sony Corporation
Samsung Electronics Co., Ltd.
Bose Corporation
Sonos, Inc.
Sennheiser electronic GmbH & Co. KG
Audio-Technica Corporation
Shure Incorporated
Other companies operating in the Audio Market include Harman International Industries, JBL, LG Electronics, Panasonic Holdings Corporation, Yamaha Corporation, Bang & Olufsen, and Marshall Group.
Apple competes through integrated personal audio hardware and software, while Sony maintains exposure across headphones, portable audio, home entertainment, and professional products. Competitive differentiation increasingly depends on wireless connectivity, acoustic engineering, software, ecosystem integration, battery performance, ANC, spatial audio, and intelligent processing.
Conclusion
The Audio Market is projected to grow from USD 95.40 billion in 2026 to USD 145.35 billion by 2034, registering a CAGR of 5.20% during the forecast period. The market is being shaped by wireless connectivity, computational audio, connected ecosystems, smart speakers, automotive audio, professional equipment, and emerging broadcast technologies such as Auracast.
Headphones & Earphones accounted for approximately 42% of the product-type segment in 2025, while wireless audio accounted for approximately 69% of the technology segment. Consumer applications represented approximately 54% of the application segment.
North America accounted for approximately 31% of global revenue in 2025, while Asia-Pacific accounted for approximately 29% and is projected to grow at approximately 6.4% CAGR through 2034.
Overall, the Audio Market continues to develop through advances in wireless connectivity, software-enabled functionality, hearing-related applications, smart-home integration, public-space broadcast audio, and connected consumer and professional audio ecosystems.
Report Link:
https://reedintelligence.com/market-analysis/audio-market