
Abrasion Resistant Steel Plate Market Size, Share & Trends Analysis Report 2026–2034
Market Overview
The global Abrasion Resistant Steel Plate Market is experiencing steady growth as mining, construction, agriculture, recycling, cement, and industrial processing industries increasingly require materials capable of withstanding repeated sliding, impact, crushing, and abrasive contact. Abrasion-resistant steel plates are designed to extend component life while reducing repair frequency, equipment downtime, and structural weight.
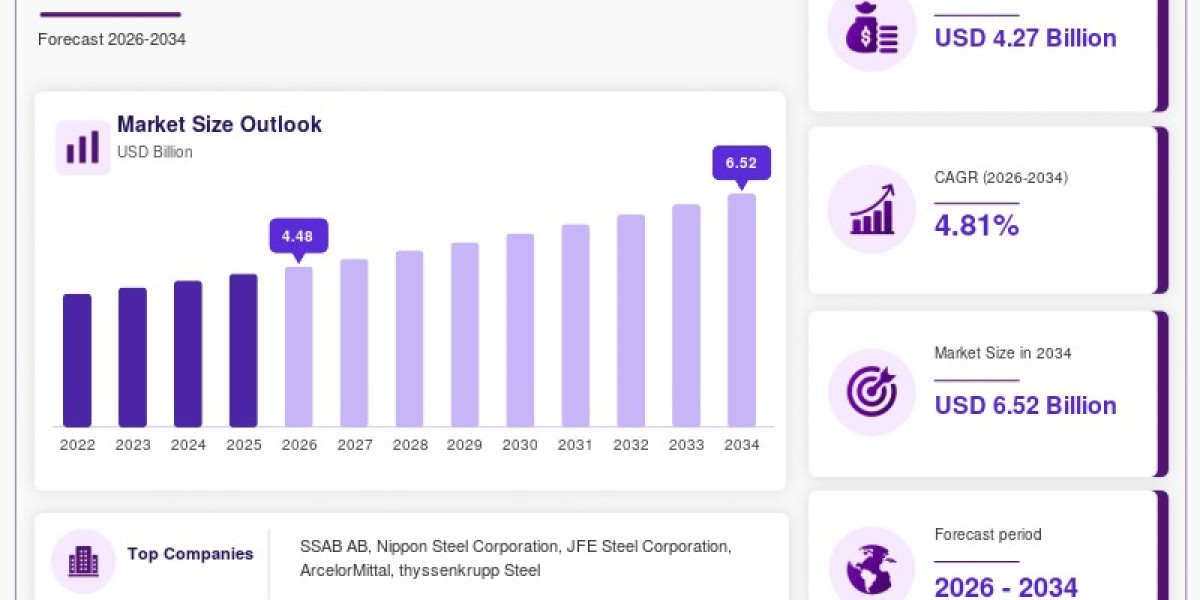
The global Abrasion Resistant Steel Plate Market was valued at USD 4.27 billion in 2025 and is projected to grow from USD 4.47 billion in 2026 to USD 6.52 billion by 2034. The market is expected to register a CAGR of 4.81% during the forecast period from 2026 to 2034.
The principal demand base includes mining, quarrying, construction equipment, material handling, cement production, recycling, agriculture, and industrial processing. Nippon Steel identifies construction machinery, industrial machinery, and transportation equipment among major applications, while JFE Steel highlights construction equipment, industrial machinery, transportation equipment, and mining machinery.
Request Sample Link:
https://reedintelligence.com/market-analysis/abrasion-resistant-steel-plate-market/request-sample
Market Size and Forecast
The Abrasion Resistant Steel Plate Market is projected to increase from USD 4.47 billion in 2026 to USD 6.52 billion by 2034, registering a CAGR of 4.81%.
Market growth is supported by the need for longer wear life in equipment exposed to severe abrasive conditions. Higher-performance plates can enable thinner wear components while maintaining required performance, creating opportunities for equipment manufacturers to reduce structural weight and potentially increase payload or improve equipment efficiency.
Mining, construction, industrial machinery, recycling, cement, and material-handling applications remain important demand areas. The market's development is also supported by product innovation focused on combinations of abrasion resistance, toughness, corrosion resistance, and temperature performance.
Market Drivers
Mining and Quarrying Equipment Requires Longer Wear Life
Mining and quarrying equipment operates continuously against rock, ore, sand, and other abrasive materials. This creates recurring demand for wear-resistant steel in mining buckets, haul-truck bodies, chutes, liners, and other components.
Higher wear resistance can extend replacement intervals and reduce maintenance interruptions. This encourages equipment manufacturers and mine operators to consider higher-performance grades where longer service life can justify additional material costs.
Higher-Performance Plates Enable Structural Weight Reduction
The combination of hardness, toughness, and strength allows manufacturers to use thinner wear components without simply increasing the risk of premature failure. Nippon Steel states that ABREX can reduce the weight of structural members exposed to severe abrasive conditions, while SSAB highlights thinner wear packages and lighter dump bodies as applications of high-performance Hardox grades.
Product Innovation Expands Wear Plate Applications
Steelmakers are developing grades designed to address combinations of abrasion, impact, corrosion, and temperature. SSAB's Hardox HiAce is designed for corrosive wear and elevated-temperature environments, while Hardox 600 targets severe-wear applications across mining, mineral processing, cement, recycling, and industrial equipment.
Market Challenges
Steel and Alloy Costs Can Limit Adoption
Abrasion-resistant plates require controlled alloy chemistry and heat treatment to achieve high hardness while retaining toughness and processability. Higher-performance grades can increase material and fabrication costs compared with conventional structural steel.
Buyers therefore evaluate additional costs against expected maintenance savings, equipment utilization, and component life. This can create stronger adoption in applications where downtime or replacement costs are substantial.
Fabrication Requirements Can Constrain Grade Substitution
High-hardness plates must balance wear resistance with cutting, bending, and welding requirements. Material substitution therefore depends not only on hardness but also on compatible fabrication processes, qualified welding procedures, and appropriate workshop capabilities.
Market Opportunities
Low-Carbon Wear Plates
Decarbonization is becoming an additional purchasing consideration for steel-intensive equipment manufacturers. SSAB introduced Hardox 450 made from SSAB Zero in 2024 and showcased the product at Bauma 2025 for construction, mining, and quarrying applications.
The opportunity is to combine wear performance with lower production-related emissions, particularly for equipment manufacturers addressing supplier-emissions targets.
Corrosion-Resistant Wear Plate
Equipment operating in wet, acidic, or corrosive environments can experience accelerated material degradation. SSAB developed Hardox HiAce for situations where abrasion and corrosion occur together, including waste and recycling, pulp and paper, sawmills, biomass, and process industries.
This creates opportunities for specialized wear plates that can address combined corrosion and abrasion while maintaining suitable fabrication characteristics.
Market Segmentation
The Abrasion Resistant Steel Plate Market is segmented by Product Type, Application, Thickness, and Region.
By Product Type
AR450
AR450 accounted for approximately 34% of the global market in 2025, making it the largest product-type segment. Its position reflects the demand for a balance of abrasion resistance, toughness, and processability.
AR500
AR500 represented approximately 27% of the market in 2025 and is projected to grow at a CAGR of approximately 5.1%. Its higher hardness makes it suitable for severe wear conditions, including liners, crusher components, and other wear-intensive applications.
AR400
AR400 accounted for approximately 23% of the market in 2025, with a CAGR of approximately 4.3%.
AR600
AR600 represented approximately 10% of the market in 2025 and is projected to grow at approximately 5.0% CAGR. Its adoption is associated with severe-wear applications where conventional grades may require more frequent replacement.
Others
Other product types represented the remaining 6% of the market, with a CAGR of approximately 4.0%.
By Application
Mining accounted for approximately 39% of the market in 2025, making it the largest application segment. Construction represented approximately 24% and is projected to grow at approximately 4.9% CAGR.
Agriculture accounted for 11%, recycling and waste management 9%, cement and concrete 8%, and other applications 9%.
Recycling and waste management is projected to grow at approximately 6.0% CAGR, making it the fastest-growing application segment. The segment includes equipment exposed to abrasion, impact, moisture, and corrosion.
By Thickness
Plates between 21 and 50 mm represented approximately 46% of the market in 2025, making this the largest thickness category.
Above 50 mm plates accounted for approximately 31% and are projected to grow at approximately 4.9% CAGR. Up to 20 mm plates represented approximately 23% of the market and are projected to grow at approximately 4.5% CAGR.
Regional Analysis
Asia-Pacific
Asia-Pacific accounted for approximately 42% of the global market in 2025, making it the largest regional market. The region combines major steelmaking capacity with extensive mining, construction equipment, infrastructure, and industrial machinery activity.
Asia-Pacific is also the fastest-growing region, with approximately 5.4% CAGR through 2034.
North America
North America represented approximately 25% of the market in 2025 and is projected to grow at approximately 4.7% CAGR. Demand is supported by mining, aggregates, construction equipment, waste processing, and heavy-duty transportation applications.
Europe
Europe represented approximately 20% of the market in 2025 and is projected to grow at approximately 4.3% CAGR. The regional market is supported by heavy-equipment, steel-processing, recycling, and industrial machinery industries.
Latin America
Latin America accounted for approximately 8% of the market in 2025 and is projected to grow at approximately 4.8% CAGR. Mining and mineral-processing applications create an important demand base for abrasion-resistant steel plates.
Middle East & Africa
Middle East & Africa represented approximately 5% of the market in 2025 and is projected to grow at approximately 4.6% CAGR. Demand is concentrated in construction machinery, quarrying, mining, cement production, and material handling.
Key Players
SSAB AB
Nippon Steel Corporation
JFE Steel Corporation
ArcelorMittal
thyssenkrupp Steel
voestalpine AG
Tata Steel
Baosteel
The competitive landscape is based on grade consistency, toughness, weldability, formability, thickness range, application engineering, product availability, and lifecycle performance.
SSAB has developed a broad Hardox portfolio covering standard structural wear grades and specialized products for severe, corrosive, and high-temperature environments. Nippon Steel competes through its ABREX series, emphasizing abrasion resistance together with weldability, bending performance, and weight reduction.
Conclusion
The Abrasion Resistant Steel Plate Market is projected to grow from USD 4.47 billion in 2026 to USD 6.52 billion by 2034, registering a CAGR of 4.81%. Mining, construction, industrial machinery, recycling, cement, agriculture, and material-handling applications continue to support demand for materials capable of delivering longer wear life and reducing maintenance requirements.
AR450 currently represents the largest product-type segment with approximately 34% of the market, while mining leads applications with approximately 39%. Asia-Pacific remains the largest regional market with approximately 42% of global share and is projected to record the fastest regional CAGR of approximately 5.4% through 2034.
The market continues to present opportunities through low-carbon wear plates, corrosion-resistant materials, higher-performance grades, and applications requiring improved durability and lifecycle performance.
Report Link:
https://reedintelligence.com/market-analysis/abrasion-resistant-steel-plate-market