
AEC Software Market Size, Share, Demand, Growth & Forecast 2026–2034
Market Overview
The AEC Software Market is experiencing strong growth as architecture, engineering, construction, and operations organizations increasingly adopt digital platforms to improve project delivery, collaboration, and lifecycle management. AEC software encompasses digital platforms and applications supporting architecture, engineering, construction, and the broader built-environment lifecycle. These solutions cover Building Information Modeling (BIM), computer-aided design, construction planning, project management, estimating, documentation, collaboration, and asset operations.
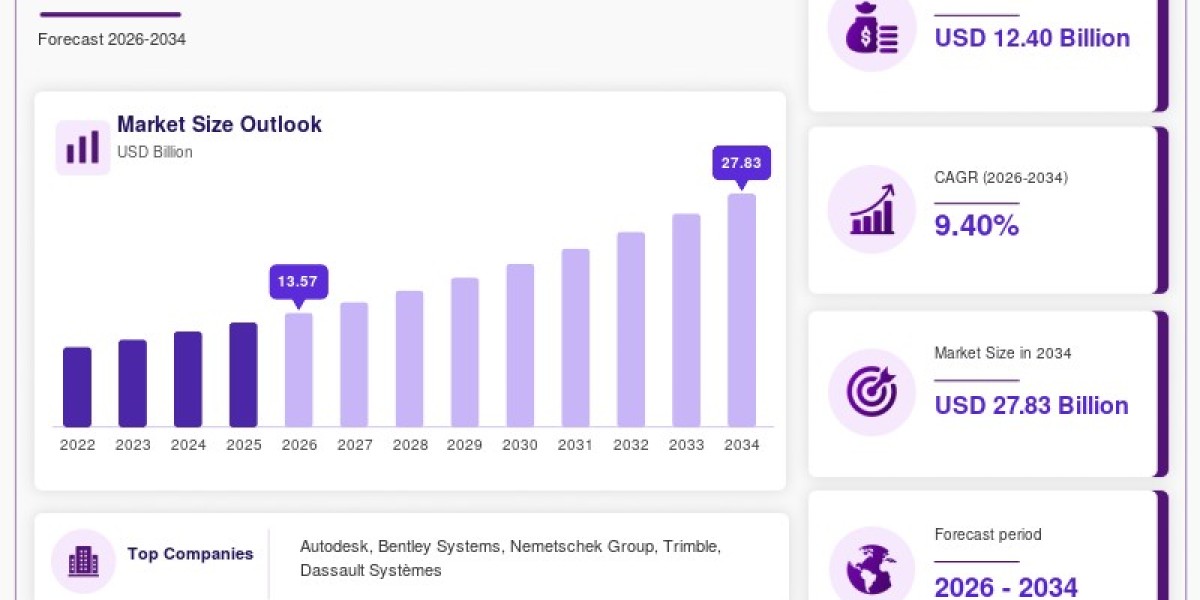
The global AEC software market was valued at USD 12.40 billion in 2025 and is projected to grow from USD 13.57 billion in 2026 to USD 27.83 billion by 2034. The market is registering a CAGR of 9.40% during the forecast period from 2026 to 2034. The market is shifting from standalone desktop applications toward cloud-connected, collaborative, and data-centric platforms that connect design, construction, and operational workflows.
Request Sample Link:
https://reedintelligence.com/market-analysis/aec-software-market/request-sample
Market Size and Forecast
The global AEC software market is projected to increase from USD 13.57 billion in 2026 to USD 27.83 billion by 2034, expanding at a CAGR of 9.40% during 2026–2034. The market's development is supported by increasing adoption of BIM, cloud collaboration, artificial intelligence, and connected digital workflows across architecture, engineering, and construction.
The transition toward cloud-based platforms is also influencing market development. Cloud deployment enables project teams to access models, drawings, documents, and project information across different locations while facilitating continuous information exchange between design and construction teams.
The market is also expanding as software providers increasingly connect design, construction, and operational workflows, allowing project information to move across different project stages without repeated manual conversion.
Market Drivers
Increasing Adoption of BIM Accelerates Demand for Integrated AEC Software
Building Information Modeling has become an important foundation for digital project delivery because it enables project participants to work with coordinated digital representations of buildings and infrastructure. BIM supports design coordination, clash detection, documentation, quantity estimation, and information exchange across project stages.
As construction projects become more complex, organizations increasingly require platforms that allow architects, engineers, contractors, and owners to collaborate around a common project model. Software providers are therefore expanding BIM functionality while improving interoperability with other design, analysis, and construction-management tools.
Cloud Collaboration Is Reshaping AEC Workflows
Cloud deployment allows project teams to access models, drawings, documents, and project information from different locations. This is particularly valuable for construction projects involving multiple organizations and geographically distributed teams.
In March 2026, Autodesk announced that Autodesk Construction Cloud had become Autodesk Forma, integrating construction capabilities into its broader AECO industry cloud. Cloud-based workflows can reduce reliance on locally stored files and facilitate more continuous information exchange between design and construction teams.
AI Adoption Is Expanding Across Architecture, Engineering and Construction
Artificial intelligence is increasingly being integrated into AEC software to automate repetitive activities, improve design exploration, and support project decision-making.
Autodesk announced in September 2026 that it was expanding agentic AI across Autodesk Forma, including capabilities designed to use connected project data and context to support users across products and teams. Nemetschek has similarly expanded AI capabilities across its AEC portfolio, including AI-assisted design and its AI Assistant across solutions such as Archicad and ALLPLAN.
Market Challenges
High Implementation Costs Can Restrict Adoption Among Smaller Firms
Advanced AEC platforms can require substantial investments in software licenses, hardware, cloud infrastructure, training, and implementation services. Smaller architecture and construction firms may face difficulty absorbing these costs, particularly when migrating from familiar legacy applications.
Although subscription and cloud models can reduce upfront expenditure, recurring software costs remain an important consideration for smaller organizations.
Interoperability Challenges Remain Across AEC Software Ecosystems
AEC projects frequently involve software from multiple vendors. Architects, structural engineers, contractors, and owners may use different platforms for BIM, analysis, construction management, and asset management.
Moving information between these environments without loss of data, geometry, or project context remains challenging. Open standards such as IFC can help, but differences in data structures and software capabilities can still create workflow friction.
Shortage of Digitally Skilled Professionals Can Slow Deployment
Effective use of advanced BIM, cloud, and AI tools requires professionals with specialized digital skills. Firms may need to train architects, engineers, contractors, and project managers to adopt new workflows.
Organizations with limited internal IT and digital-transformation resources may therefore experience longer implementation cycles.
Market Opportunities
AI-Assisted Design Creates New Software Capabilities
AI can assist with early-stage design exploration, visualization, documentation, analysis, and project information retrieval. Autodesk's Forma platform incorporates AI-powered tools for pre-design and schematic design, while its broader strategy connects early-stage design with detailed Revit workflows.
This creates opportunities for vendors to offer intelligent design assistance while maintaining established modeling and documentation environments.
Digital Twins Expand the Role of AEC Software Beyond Construction
Digital twins connect digital representations with information about physical assets and their operational conditions. This expands the role of AEC software from project design and construction into facility management, infrastructure operations, and lifecycle optimization.
Infrastructure software vendors are increasingly combining engineering models, asset information, and AI capabilities to support ongoing infrastructure management. Bentley Systems, for example, has been expanding infrastructure AI capabilities and integrating engineering and infrastructure data into connected workflows.
Integrated Construction Planning Supports Growth in Cloud Platforms
Construction planning increasingly requires coordination of schedules, models, resources, costs, and site information. Integrated 4D and 5D workflows can connect project schedules and cost information to digital models.
Bentley introduced SYNCHRO+ in 2025 as an AI-powered approach to 4D construction planning, with integration through Bentley Infrastructure Cloud and planned general availability in 2026.
Market Segmentation
The AEC Software Market is segmented by Solution Type, Deployment, Application, End User, and Region.
By Solution Type
Building Information Modeling
Building Information Modeling accounted for approximately 34% of the global AEC software market in 2025, making it the largest solution segment. BIM supports coordinated digital modeling across architectural, structural, MEP, and construction workflows. Its adoption is supported by the need to reduce design conflicts, improve documentation, and coordinate information between project stakeholders.
Construction Management
Construction Management accounted for approximately 21% of the market and is projected to grow at approximately 10.3% CAGR, making it the fastest-growing major solution segment. Cloud-based construction management is gaining relevance as contractors seek integrated tools for scheduling, field coordination, documentation, and project communication.
Other Solution Types
Computer-Aided Design represented approximately 20%, Project Management 13%, Cost Estimation & Analysis 7%, and other solutions approximately 5%.
By Deployment
Cloud-Based
Cloud-based AEC software accounted for approximately 58% of the market in 2025, making it the largest deployment segment. Cloud platforms enable remote access, centralized project information, real-time collaboration, and easier software updates.
Cloud-based deployment is also the fastest-growing segment, with approximately 11.2% CAGR through 2034.
On-Premise
On-premise deployment accounted for approximately 42% of the market in 2025 and is projected to grow at approximately 6.7% CAGR.
By Application
Engineering
Engineering accounted for approximately 31% of the market in 2025, making it the largest application segment. Engineering firms rely on AEC software for structural design, civil engineering, MEP systems, infrastructure modeling, analysis, and technical documentation.
Construction
Construction accounted for approximately 28% and is projected to grow at approximately 10.5% CAGR, making it the fastest-growing major application segment. Construction organizations are adopting digital project-management, BIM coordination, 4D planning, and field-management tools to improve project visibility.
Architecture represented approximately 24%, while Operations & Maintenance accounted for approximately 17%.
By End User
Contractors
Contractors accounted for approximately 32% of the global market in 2025, making them the largest end-user segment. Contractors increasingly use AEC software for construction planning, scheduling, BIM coordination, estimating, procurement, field management, and project documentation.
Developers represented approximately 18% and are projected to grow at approximately 10.1% CAGR. Engineers represented approximately 27%, architects 18%, and other end users approximately 5%.
Regional Analysis
North America
North America accounted for approximately 36% of the global AEC software market in 2025, making it the largest regional market. The region benefits from mature construction technology adoption, established BIM practices, large software vendors, and significant investment in infrastructure and commercial development.
The presence of major AEC software providers and strong demand for cloud-based collaboration further supports the regional market.
Europe
Europe represented approximately 29% of the market in 2025 and is projected to grow at approximately 8.4% CAGR. The region has established BIM adoption across architecture, engineering, and construction and continues to emphasize digital project delivery, sustainability, and building-performance analysis.
Nemetschek's continued expansion of cloud and AI capabilities across its software ecosystem reflects the movement toward intelligent digital workflows in the region.
Asia-Pacific
Asia-Pacific accounted for approximately 25% of the market and is projected to grow at approximately 11.2% CAGR, making it the fastest-growing major region. Rapid urbanization, infrastructure development, digital construction initiatives, and increasing adoption of BIM and cloud technologies are supporting regional expansion.
Japan, China, India, South Korea, and Southeast Asian markets are contributing to demand for BIM, CAD, construction management, and project collaboration platforms.
Latin America
Latin America accounted for approximately 6% of the market in 2025 and is projected to grow at approximately 8.2% CAGR. Construction companies are increasingly adopting digital tools to improve project documentation, scheduling, estimating, and collaboration.
Middle East & Africa
Middle East & Africa accounted for approximately 4% of the market in 2025 and is projected to grow at approximately 9.1% CAGR. Large infrastructure, urban development, and construction projects across the Gulf region are supporting adoption of BIM, project-management, and digital construction platforms.
Key Players
Autodesk
Bentley Systems
Nemetschek Group
Trimble
Dassault Systèmes
Hexagon
RIB Software
Procore Technologies
Other companies covered in the market include Oracle and Graphisoft.
Competition in the AEC software market is centered on BIM capabilities, cloud connectivity, interoperability, AI functionality, project lifecycle coverage, collaboration tools, and integration with existing design and construction systems. Leading vendors are increasingly developing connected ecosystems rather than isolated applications.
Recent developments include Autodesk's March 2026 announcement that Autodesk Construction Cloud had become Autodesk Forma, advancing its strategy for a unified industry cloud covering architecture, engineering, and construction.
Autodesk also announced in 2025 that Revit would become the first Forma Connected Client, enabling deeper integration between the desktop BIM environment and its cloud platform. In 2026, Autodesk expanded this approach so Revit users could access selected Forma capabilities involving project context, analysis, and connected cloud workflows.
Conclusion
The AEC Software Market is projected to grow from USD 13.57 billion in 2026 to USD 27.83 billion by 2034 at a CAGR of 9.40%. Increasing adoption of BIM, cloud collaboration, artificial intelligence, digital twins, and integrated construction planning will continue to support market development.
Building Information Modeling currently leads the solution type segment with approximately 34% of the market, while cloud-based deployment leads with approximately 58%. Engineering represents the largest application segment at approximately 31%, and contractors account for the largest end-user share at approximately 32%.
North America remains the largest regional market with approximately 36% of the global market, while Asia-Pacific is projected to record the fastest regional CAGR of approximately 11.2% through 2034.
Overall, the AEC Software Market continues to present opportunities across AI-assisted design, cloud collaboration, digital twins, BIM, integrated construction planning, and connected lifecycle-management platforms as architecture, engineering, and construction organizations increasingly adopt digital workflows.
Report Link:
https://reedintelligence.com/market-analysis/aec-software-market