
Understanding the Forces Reshaping Chemical Markets
Chemical prices are influenced by a complex relationship between raw material availability, production costs, plant operating rates, international logistics, and downstream purchasing decisions. A change in feedstock prices does not always translate into an equivalent increase in finished chemical prices, particularly when buyers resist higher offers or manufacturers face weaker demand.

Chemicals pricing intelligence helps businesses understand these interconnected market forces through price assessments, supply-demand analysis, regional comparisons, and forward-looking market insights. For chemical manufacturers, procurement teams, distributors, and industrial buyers, this information supports purchasing decisions, supplier evaluations, and cost management.
Grand View Signal's Chemicals Monthly Pricing Intelligence covers organic, inorganic, and specialty chemicals, providing insights into market movements and the factors influencing chemical prices across different regions.
Chemicals Pricing Intelligence: September 2026 Market Overview
September 2026 recorded selective price strength across chemical markets, driven primarily by supply availability, feedstock costs, and regional production economics rather than broad-based demand growth.
Key market developments included:
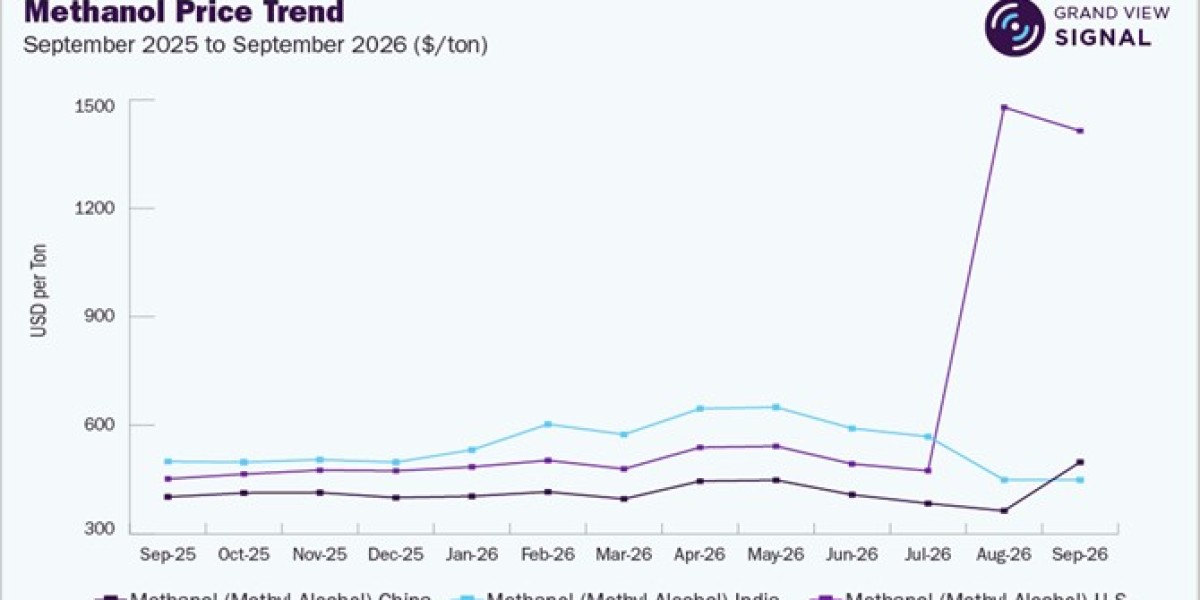
Methanol: Tight coastal availability and limited import arrivals supported Chinese prices. Methanol emerged as the top-performing chemical commodity, with average month-on-month growth of 7.4% across the top three geographies covered in the assessment.
Aromatics and organic intermediates: Chinese industrial petroleum benzene and glacial acetic acid prices increased 6.5% and 17.4%, respectively, during September 11–20 compared with September 1–10.
Acetate solvents: Higher acetic acid costs supported ethyl acetate and butyl acetate, although cautious buying limited price increases. Ethyl acetate rose nearly 0.3% during September 21–24, while butyl acetate increased 1.5% during September 17–24.
Inorganic chemicals: Chinese sulphuric acid prices declined 3.2% during September 11–20 compared with the preceding ten-day period, while caustic soda remained unchanged over the same reporting period.
Specialty chemicals: Chinese sodium persulfate indications strengthened, with prices for material of at least 99% purity moving from CNY 7,175–7,225 per ton during September 14–20 to CNY 7,300–7,400 during September 21–27.
These developments demonstrate that chemical pricing trends vary considerably by product, region, feedstock exposure, and purchasing behaviour.
Schedule a free demo of Grand View Signal to get a real-time preview of price fluctuations in the chemicals sector
Major Categories of Chemicals Pricing Intelligence
1. Organic Chemicals
Organic chemicals include alcohols and glycols, amines and nitrogenous organics, aromatics and olefins, monomers and resin intermediates, organic acids and anhydrides, plasticizers, and solvents, ketones and esters.
During September, tighter methanol availability in China supported prices, while higher acetic acid costs increased pressure across related chemical chains. However, downstream products experienced different degrees of price movement.
Ethyl acetate buyers resisted higher offers and largely purchased according to immediate requirements. Butyl acetate received support from higher acetic acid costs and slightly lower operating rates, although declining n-butanol prices partly offset that pressure.
Key insight: Rising feedstock costs do not guarantee equivalent price increases across downstream chemicals. Manufacturers must consider input costs alongside operating rates, inventories, customer demand, and their ability to pass through higher expenses.
2. Inorganic Chemicals
Inorganic chemicals include alkalis and bases, halogens and fluorochemicals, boron and silicon compounds, inorganic salts, mineral acids, and sulphur and carbon products.
September conditions were mixed. Chinese sulphuric acid prices softened during the middle of the month, while caustic soda remained stable. At the same time, international sulphur supply pressures continued to influence phosphoric-acid production economics.
For import-dependent producers, the availability and reliability of sulphur deliveries can be as important as the quoted input price. These conditions are particularly relevant to phosphate-processing supply chains.
Key insight: Local chemical prices may diverge from international feedstock pressures because domestic production, import dependence, inventories, and industrial consumption differ by market.
3. Specialty Chemicals
Grand View Signal's specialty chemicals coverage includes ammonium persulfate, sodium hypochlorite, sodium persulfate, and hydrogen peroxide.
During September, Chinese sodium persulfate indications recovered between the middle and latter part of the month. Its applications in polymerization, electronics processing, and bleaching connect pricing conditions with requirements across different industrial sectors.
Key insight: Specialty chemical assessments should account for product-specific applications, purity requirements, supplier quotations, and end-use demand instead of assuming that all products respond similarly to broader chemical market movements.
Get historical, current, and forecast chemicals price assessments. Request Free Access to Grand View Signal
Key Drivers Influencing Chemical Prices
Feedstock Availability and Logistics
Middle Eastern shipping disruptions continued to influence hydrocarbon feedstock availability. By late September, UAE and Kuwaiti naphtha exports to Asia were recovering through alternative arrangements, including transfers outside the Strait of Hormuz and loading through Fujairah. However, logistical constraints and exports remaining below year-earlier levels indicated that supply had not fully normalized.
Energy Costs and Production Economics
High natural gas costs affected European chemical manufacturing competitiveness. In the UK, the announced idling of three acetyls plants at Hull highlighted the impact on acetic acid, acetic anhydride, and ethyl acetate production.
This illustrates how elevated production costs can constrain supply even when downstream demand remains weak.
Downstream Demand and Cost Pass-Through
Chemical producers cannot always transfer higher feedstock costs to customers. September's acetate solvent market demonstrated how cautious purchasing limited price increases despite upstream cost pressure.
For buyers and manufacturers, the balance between replacement costs, available supply, and customer purchasing requirements remains essential to understanding pricing power.
Get detailed driver impact analysis on Chemicals Prices. Request Free Access to Grand View Signal
How Chemicals Pricing Intelligence Supports Procurement Strategy
Chemicals pricing intelligence helps procurement and commercial teams compare regional prices, monitor feedstock movements, assess supply risks, and evaluate changes in production economics.
Historical assessments and forecasts can also support budgeting, supplier negotiations, and purchasing plans. By distinguishing between temporary supply constraints and broader changes in demand, businesses can make more informed decisions about procurement timing and sourcing alternatives.
Grand View Signal provides chemical price assessments across organic, inorganic, and specialty categories, supported by historical data, current market analysis, and forward-looking assessments.
Access commodity-wise monthly forecast datasets for the next 6 months. Request Free Access to Grand View Signal
Turning Chemical Market Signals into Better Decisions
September 2026 highlighted three important relationships: tight feedstock availability can support prices, high energy costs can constrain production, and downstream resistance can limit cost pass-through. Their combined effects explain why different chemical products can follow different price directions during the same period.
For procurement professionals and chemical manufacturers, the objective is to understand not only how prices change, but also which supply-chain conditions are driving those changes and how they affect purchasing costs and operating margins.
Enhance your understanding of the key factors affecting commodity prices and boost your procurement strategy with Grand View Signal. Explore the platform @ https://www.grandviewresearch.com/horizon/signal
Read Our Latest Blogs On
- Lithium Price Crash 2026: Oversupply, Jianxiawo Mine, and What Comes Next
- LNG Procurement Strategy: Managing Geopolitical and Supply Risks
- Thermal Coal Prices 2026: Asia's Fuel Security vs. the Energy Transition
- How Energy Price Volatility Adds Hidden Costs to Your Commodity Supply Chain
- Uranium Price Intelligence: The Nuclear Revival and What It Means for Fuel Buyers