A boat owner may expect the amount listed on an insurance policy to match what the vessel could sell for in the current market. In practice, these figures can be different because they serve separate purposes. A sale price reflects what a buyer is willing to pay in a particular transaction, while an insurance valuation is connected to the terms of the policy and the financial protection agreed upon with the insurer.
Understanding this distinction matters when purchasing coverage, renewing a policy, upgrading a vessel, or preparing for a potential claim. Knowing how insurers and buyers approach value can help owners ask better questions, maintain useful records, and avoid assuming that one figure automatically determines the other.
What an Insurance Valuation Actually Represents
An insurance valuation is used to establish the financial basis for coverage under a marine insurance policy. Depending on the insurer and policy wording, the arrangement may use an agreed value, actual cash value, or another valuation method. These terms are not interchangeable, and the policy determines how a covered loss is evaluated.
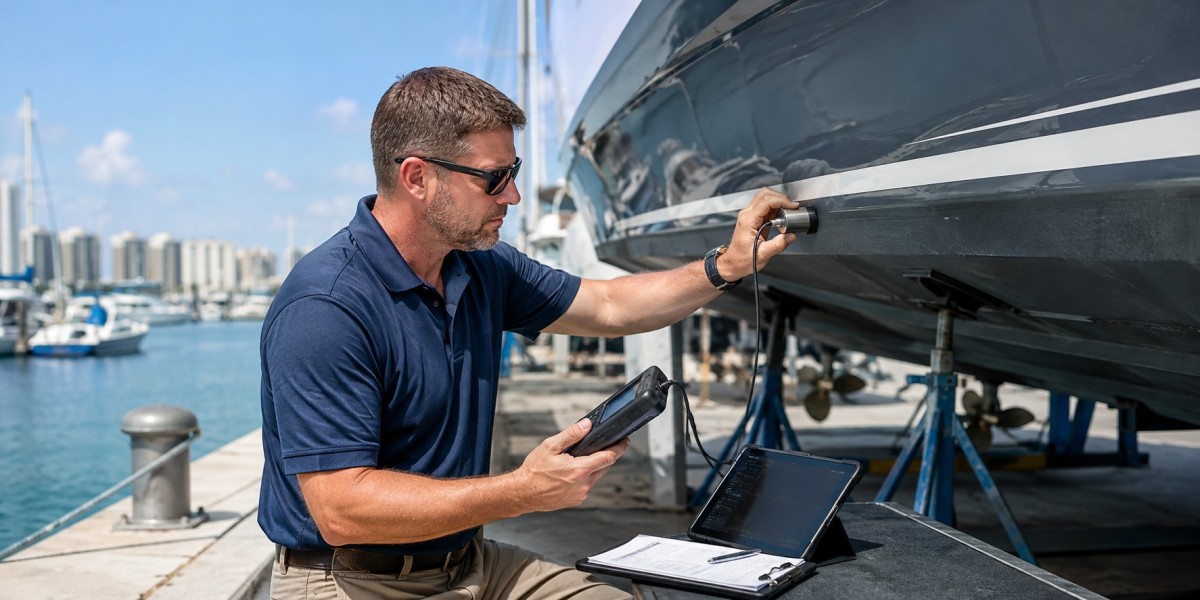
A marine appraisal can help establish a vessel's condition and market position. Factors such as age, maintenance history, equipment, upgrades, structural condition, and comparable sales can influence the assessment. Owners comparing these factors can learn more about insurance value and the details that may affect a boat's appraised worth.
The important point is that an appraisal figure does not automatically become the amount an insurer will pay. The policy's valuation basis, coverage limits, deductibles, exclusions, and claim provisions all matter. Owners should review the actual policy documents rather than relying only on a number shown in an appraisal or insurance application.
Why the Sale Price Can Be Different
A boat's sale price is shaped by a specific transaction. The buyer may be comparing several vessels, negotiating over repairs, or placing a premium on equipment that suits their intended use. The seller's urgency and local demand can also influence the final amount.
Insurance valuation follows a different process. It may consider the vessel's characteristics and condition alongside the insurer's underwriting approach and the policy terms. As a result, a recent purchase price is useful information, but it may not settle the question of appropriate coverage.
For example, a buyer might purchase an older fishing boat at a reduced price because the seller wants a quick transaction. That price reflects the circumstances of the sale. Another owner with a similar model, better maintenance records, and recently installed equipment may have a different valuation. Conversely, expensive modifications do not always increase a boat's market or insured value by the full amount spent.
How Policy Valuation Methods Affect the Difference
The wording of a marine insurance policy is central to understanding what happens when a vessel is damaged or becomes a total loss.
Agreed value coverage generally establishes a value between the insurer and policyholder when the policy is written. The amount and the conditions governing payment are set out in the contract. Owners should still review provisions concerning deductibles, partial losses, exclusions, and other limitations.
Actual cash value coverage commonly considers depreciation and the vessel's value at the time of loss. Age, condition, wear, and market evidence may therefore affect the calculation. A boat that has lost value over several years may not receive the same valuation it had when the policy began.
Some policies use stated values or other specialized terms. The practical meaning can vary, so owners should not assume that a stated amount always guarantees a particular claim payment. Asking the insurer to explain the valuation clause before binding coverage can prevent misunderstandings later.
Factors That Influence a Boat’s Market and Appraised Value
Several characteristics can affect what a boat is worth, whether the figure is being considered for a sale, appraisal, or insurance discussion.
Age and condition: Age provides useful context, but physical condition can be equally important. Hull damage, corrosion, moisture intrusion, worn machinery, and neglected systems may affect a vessel differently from one that has been consistently maintained.
Maintenance and repair records: Service invoices, engine maintenance records, receipts for repairs, and documentation of significant work help establish the vessel's history. Clear records can make it easier to understand what has been maintained or replaced.
Equipment and upgrades: Navigation electronics, propulsion systems, generators, safety equipment, and other installed features may influence a boat's appeal. Their contribution depends on age, functionality, installation quality, and relevance to likely buyers.
Comparable sales: Recent transactions involving similar vessels can provide useful market context. Comparisons are more meaningful when they account for model, year, size, equipment, condition, and location rather than relying on asking prices alone.
Structural condition: The condition of the hull, deck, bulkheads, and other structural components can affect a buyer's willingness to purchase a vessel and an appraiser's assessment. Visible defects or evidence of previous repairs may require further examination.
These factors do not produce one universal number. Their importance depends on the vessel, the purpose of the valuation, and the information available.
Why Owners Should Review Coverage After Major Changes
A boat's condition and equipment can change considerably during ownership. An engine replacement, electronics upgrade, substantial refit, or major repair may affect its market appeal and the information an insurer has on file.
Owners should keep invoices, photographs, maintenance records, and details of installed equipment. They should also contact their insurer when a change may affect the vessel's value or the terms of coverage. The insurer can explain whether updated documentation, a revised appraisal, or a policy adjustment is appropriate.
This review is particularly useful before renewal. A policy established years earlier may no longer reflect the vessel's current configuration or the owner's expectations. However, owners should not assume that every improvement increases the insured amount automatically. The insurer must confirm any change to the coverage.
What to Check Before Relying on a Valuation
Before accepting an insurance figure, owners should understand its purpose and limitations. Check whether it represents an agreed value, an estimate of current market value, or another figure used for underwriting. Confirm the valuation date and whether the report reflects the vessel's present condition.
It is also worth checking whether trailers, tenders, electronics, personal property, and specialized equipment are included or insured separately. Coverage for these items depends on the policy wording. Owners should ask how deductibles, depreciation, salvage, and exclusions may affect a claim.
A marine appraisal can provide supporting information, but it is not a substitute for reading the policy. The insurer is responsible for explaining the coverage it offers and the conditions that apply.
Conclusion
A boat's insurance value and sale price may differ because they are based on different purposes, methods, and circumstances. The sale price reflects a particular buyer and transaction, while the insurance figure is governed by the policy's valuation terms and underwriting process.
Owners can make better coverage decisions by understanding the valuation method, keeping accurate maintenance and upgrade records, and reviewing insurance after significant changes to the vessel. A clear appraisal and a careful reading of the policy help reduce uncertainty when determining whether the coverage reflects the boat and the owner's needs.